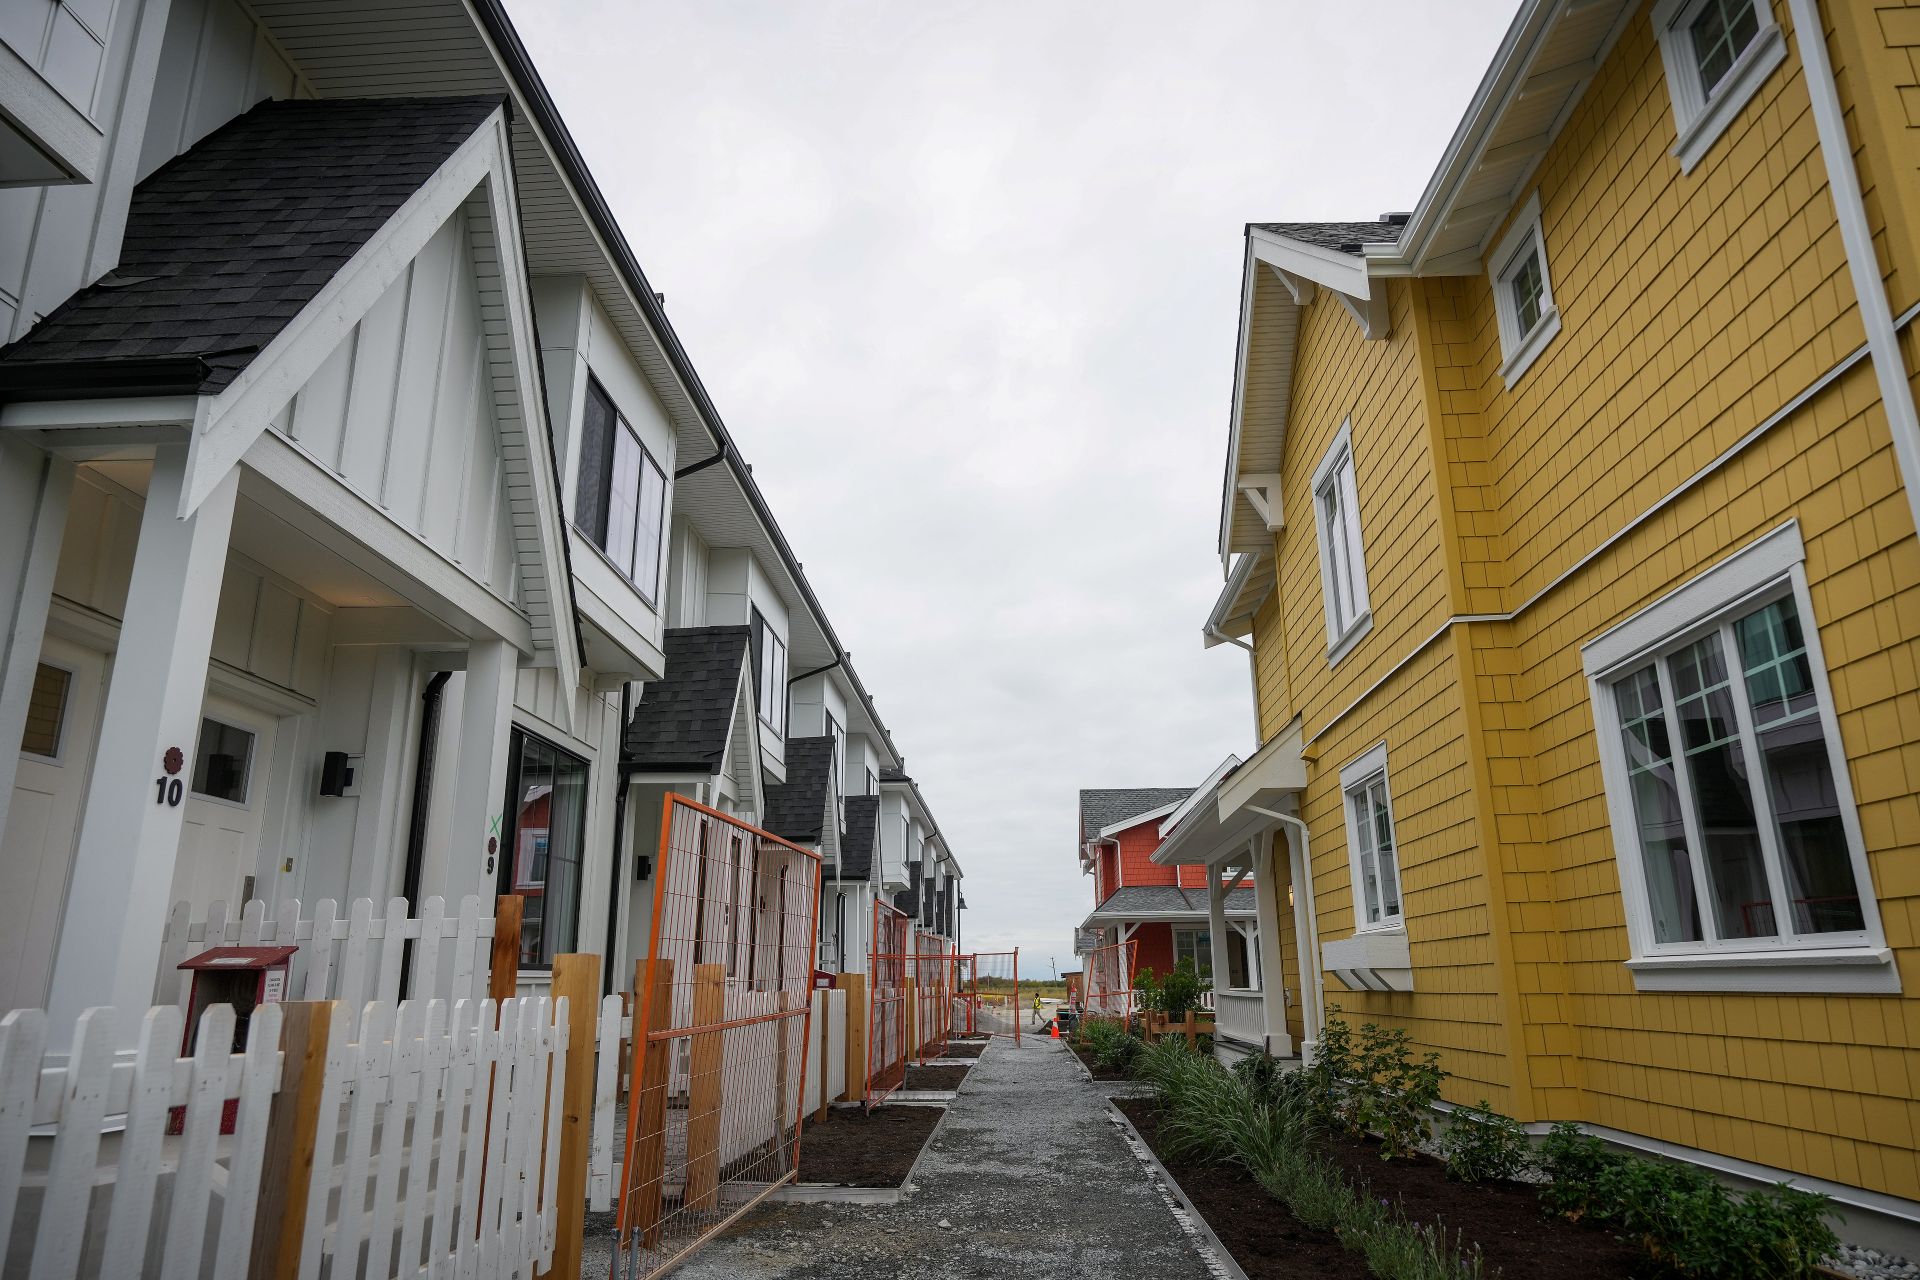
When a housing co-operative in Kamloops, B.C., needed money to build 53 affordable, net-zero homes, part of the financing came from an unusual source – 95 individuals who chose to invest in it.
Together with a few other investors, they put $1.1 million into Propolis Housing Co-operative through community bonds, lending their money to a project they wanted to see built and earning a financial return in exchange.
At a moment when Canada is searching for more investment, Propolis is an example of an overlooked source of capital – the savings of ordinary Canadians. If we want more of that money for viable projects in our communities, those investments need to be easier to make and more financially attractive for Canadians.
Community wealth building is a strategy for Canada’s transition to net zero
Foundations ought to be investing in infrastructure
A million new non-market homes in 10 years: That should be the goal
Current federal tax law puts up a roadblock. Many community bonds do not easily qualify to be held in RRSPs or TFSAs, which puts them at a tax disadvantage compared with investments that can be held in registered accounts. Existing rules can require community debt investments to be asset-backed or mortgage-backed to qualify – a costly and complicated hurdle for many smaller issuers.
The Canadian Coalition for Community Capital, representing more than 30 organizations across the country, proposes three steps to rectify these problems:
- making eligible community investments easier to hold in RRSPs and TFSAs;
- introducing a 30-per-cent community capital tax credit;
- allowing investors to count a portion of eligible losses for tax purposes.
It is also calling for changes that would make it easier for co-operatives to raise capital beyond their existing membership and for creating stronger intermediaries to connect projects with investors.
Great potential exists
Despite the existing barriers, more than 6,000 Canadians have invested at least an estimated $170 million through community bonds, with hundreds of millions more raised through co-operative shares. That money has helped finance housing, jobs and renewable-energy projects across the country.
This demand matters because there is a particular gap in Canada’s capital market that everyday Canadians are well-suited to fill. A $5-million housing project or $15-million community facility can be too small to attract a pension fund or major institutional investor, but far too large to be financed through grants and donations alone. These are viable projects that communities need, but they often struggle to assemble the capital required to get built.
The potential pool of capital is significant. Canadians held roughly $4 trillion in savings and financial assets in 2024. The question is whether we have good enough channels to connect even a small portion of that money with projects being built in our communities.
We know the model works. The question now is whether we want it to remain a relatively small corner of Canada’s capital market or whether we build the infrastructure that would allow it to scale.
The benefits could be huge
Independent modelling commissioned by the coalition estimates that its three proposed tax measures (above) could mobilize $385 million to $831 million (page 11) in community capital over five years.
The federal government already uses this principle. Its new productivity mega deduction is intended to lower the after-tax cost of business investment by allowing companies to deduct a broader range of capital expenditures sooner. The policy rests on a familiar economic premise – making productive investment more attractive can draw more capital.
Community investment applies the same logic to Canadians deciding where to put their savings.
If Ottawa wants more investment in projects that communities need, it should make it easier for Canadians to put their own money behind them.
We are spending a great deal of time asking how to attract more capital to Canada. We should also be asking how to better mobilize the capital Canadians already have.