It’s only a slight exaggeration to suggest that before much of Canada was a country, it was a company – the Hudson’s Bay Company.
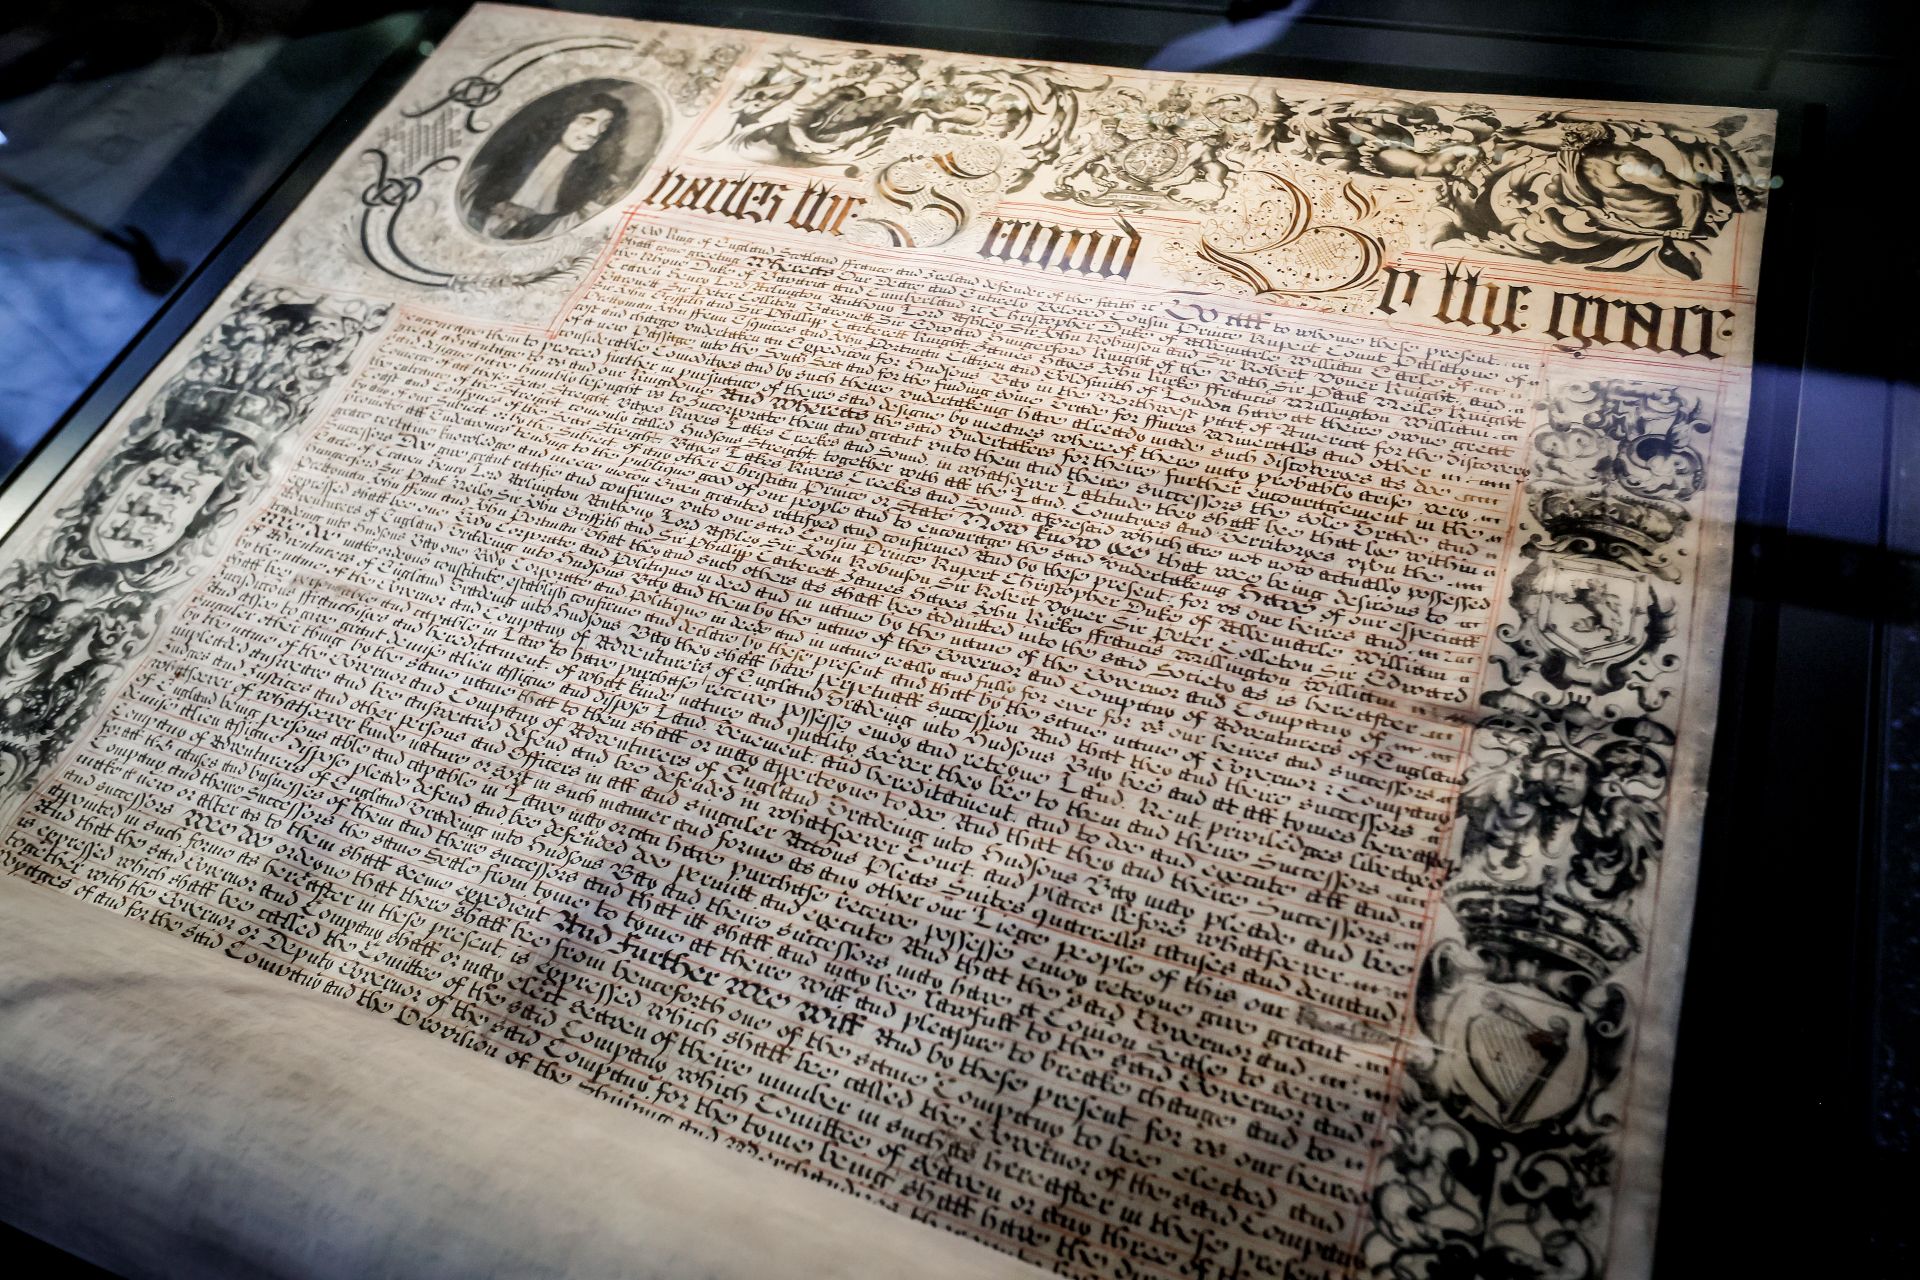
HBC was the economy, holding exclusive rights to trade and commerce. Its governance charter, the law of the land. It developed close relationships with Indigenous people, trading with them for the beaver pelts that made the company rich. It built towns, raised armies and waged wars – announcing armistices by way of corporate merger.
Then, in 2008, the company was acquired in a leveraged buyout by NRDC Equity Partners, an American private equity firm. Saddled with debt less than two decades later, the Bay unceremoniously closed its doors for good in 2025.
While for centuries HBC withstood technological changes, recessions, depressions and wars, it was the involvement of private equity that ultimately undermined HBC’s resilience.
Canadians should take note.
That’s because Canada is under economic attack, and Canadians are rightfully concerned. Heeding this sentiment, the federal government has sought to fast-track major projects, diversify our trading relationships and seek new foreign investment, all in service, ostensibly, of building a more resilient economy.
Driving business consolidation
Despite these efforts, the growing presence of private equity in Canada’s economy is undermining the quest for greater resilience. Over the last two-decades, private equity firms have bought up an astonishing amount of Canada’s economy, quietly consolidating vet clinics, funeral homes, retailers, manufacturers and everything in between. Virtually no sector of the economy has gone untouched. In 2025, PE firms were involved in 592 deals, worth more than $57 billion, across Canada.
Private equity firms, unlike traditional businesses, pool money to buy existing businesses. In turn, the acquired businesses are treated as assets in a portfolio, often to be sold again in three to seven years once the value of the acquired business has increased.
Unfortunately, this return on investment is often achieved at the expense of everything that creates economic resilience.
Indeed, research by the Harvard Business School and the University of Chicago found that businesses acquired by PE saw job losses of 4.4 per cent in the two years following an acquisition. Workers initially employed at acquired U.S. firms earned about 18 per cent less than comparable workers after three years with losses concentrated among those who left, according to data from the Centre for Economic Policy Research.
And, because PE firms generally have a short-term interest in their portfolio companies, sustainable drivers of productivity, such as training and research and development, are often eschewed for quick hits to profitability – a problem for Canada as we continue to lag our international peers in both, investing just $240 a year for each employee in the latter.
Consumers, too, suffer when PE comes to town. As PE firms roll up once-fragmented markets, they can better control pricing. In the veterinarian sector, PE consolidation has meant veterinary costs have been rising at six to eight per cent annually, comfortably outpacing inflation.
And the next generation might not get the chance to save us.
Precisely as a generation of business owners is set to retire, PE investors are bidding up business valuations, ensuring employees are priced out of future ownership opportunities. Following a PE acquisition frenzy, sales prices of vet clinics went from about three to four times earnings to 10, 20 and 30 times earnings, with similar trends observed across the economy from insurance brokers to auto-body shops to local pharmacies.
More likely to fail
And, regarding the ultimate measure of resilience, PE-owned firms come up short, as they are 10 times as likely to file for bankruptcy, compared to their non-PE counterparts.
That’s unsurprising, given the debt loads PE firms often impose on their acquisitions. Many heavily leverage their portfolio companies to purchase them in the first place, via leveraged buyouts. Other times, PE firms impose additional debt for the sole purpose of paying out shareholders, via dividend recapitalizations. In either case, economic resilience is undermined.
Boosters may argue that PE firms help re-allocate capital, and shareholders are then able to take their returns and invest in more efficient uses of capital. For example, returns squeezed out of a dying industry could be re-invested in a growth industry.
But it’s unlikely to benefit the Canadian economy as more American PE firms seek opportunity north of the border. For example, Canada’s largest payment-processing company, Moneris, was sold to U.S.-based PE firm Francisco Partners.
Moreover, PE firms fail on their own promises. Since 2006, they have largely been unable to outperform traditional equity investments. Though weak performance hasn’t stopped them from commanding hefty management fees. Worth about 1.61 per cent of all assets under management, on average, these fees add up to considerable sums considering the sheer volume of capital these firms control. In 2024, PE assets under management were estimated at US$4.7 trillion.
The evidence of the harm PE firms have on economic resilience is overwhelming. Yet, despite Ottawa’s newfound focus on strengthening economic sovereignty, little has been done to curb predatory PE buyouts.
Curbing predatory practices
Efforts to make sales of businesses to employees more attractive, such as an employee ownership trust tax incentive introduced in 2023, have largely been met with applause. But it hasn’t been enough. Mergers and acquisitions, including private equity buyouts, have largely remained steady or trended up. In 2025 alone, 301 Canadian companies were purchased by U.S. buyers.
Worse still, the productivity mega deduction, which allows businesses to immediately write off a broad range of assets, is likely to incentivize further PE acquisition because used assets and foreign buyers are not exempt from the benefit. This makes Canada all the more attractive for the US$2.51 trillion as of 2024 in financial capital waiting to be deployed by PE firms around the globe.
Until policymakers take aim at the predatory tactics of private equity firms, a resilient economy will remain out of reach in Canada.
Keeping Canadian companies in Canadian hands
Given the scale of the problem, it’s clear that simply incentivizing more socially beneficial models of ownership won’t be enough. More must be done to actively curb the negative impacts of PE on Canada’s economy.
To start, serious effort must be made to discourage PE firms from saddling companies with debt or imposing unnecessary financial risks. This means more regulation on leveraged buyouts, dividend recapitalizations and asset stripping.
Moreover, PE firms and their executives should be made directly liable to the firms they purchase, ensuring that in the event of a bankruptcy the private equity firm can’t simply walk away and must instead remain responsible for company debts and financial obligations to employees.
Legislators should also take a serious look at a complete ban on PE ownership in certain sectors, where the extractive nature of these companies can impact people at their most vulnerable, such as elder care, surgical centres or medevacs.
Because we can’t build resilience – or a country – via leveraged buyouts.